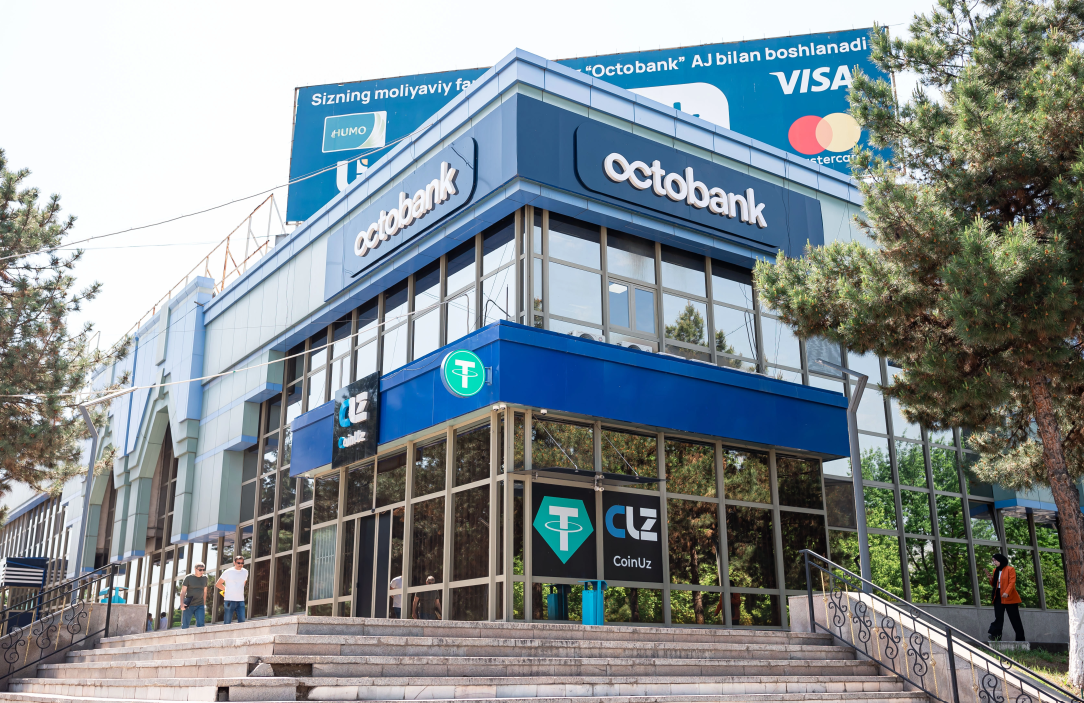
Octobank is a privately owned commercial bank in Uzbekistan that has grown quickly by building its services around mobile banking, card acquiring and digital lending. In its summary of 2025, Octobank reported a record net profit of UZS 255.9 billion (about $21.3 million), total assets of UZS 12.20 trillion (about $1.01 billion) and a place among the top three small banks in the country in the CERR rating.
This article sets out those reported results, explains what the key ratios actually tell you, and looks at the bank’s products, digital projects, international links and position in Uzbekistan’s fast-changing banking market. All figures are as published by the bank unless stated otherwise.
Octobank 2025 at a glance
The figures below come from the bank’s 2025 results announcement. US dollar amounts are the bank’s own conversions, so they depend on the exchange rate it used.
| Measure | Reported 2025 figure | Reported change |
|---|---|---|
| Net profit | UZS 255.9 billion ($21.3 million) | Record annual result |
| Total assets | UZS 12.20 trillion ($1,014.7 million) | Up $769.9 million, +314% vs 2024 |
| Customer deposits | UZS 10.84 trillion ($901.5 million) | Up $755.0 million, +515% vs 2024 |
| Return on assets | 2.1% | Down from 4.8% |
| Return on equity | 25.1% | Up from 19.9% |
| Total capital | $84.9 million | Charter capital $41.6 million plus $43.3 million other capital |
| Retail customers | More than 3.6 million | n/a |
| Businesses using acquiring | More than 15,000 | n/a |
| Foreign trade transaction volume | $3.87 billion | More than 100 foreign trade clients |
What Octobank’s financial results mean
Headline numbers are easier to judge when you know what each one measures and how they relate to each other. Here is a plain-English reading of the main figures.
Asset and deposit growth
Total assets roughly quadrupled and customer deposits grew about sixfold year on year, according to the bank. For a small bank, deposit growth on that scale usually reflects a sharp increase in customers placing money with it, which is consistent with the reported retail base of more than 3.6 million people. Deposits are the main funding source for lending, so this growth gives the bank capacity to expand its loan book.
Rapid growth cuts both ways. It shows strong customer demand, but it also means risk management, compliance and IT systems have to scale just as fast. Observers will want to see in future audited accounts whether asset quality holds up as the loan book catches up with the deposit base.
Return on assets vs return on equity
Return on assets (ROA) compares profit with the size of the balance sheet. It fell from 4.8% to 2.1%, which is what you would expect when assets grow much faster than profit in a single year: the new deposits had not yet been fully put to work.
Return on equity (ROE) compares profit with shareholders’ capital. It rose from 19.9% to 25.1%, meaning shareholders earned more on each unit of capital they had invested. A rising ROE alongside a falling ROA often signals a bank that is growing its balance sheet with more borrowed funds (deposits) relative to its own capital, so capital adequacy is worth watching as it grows.
| Ratio | What it measures | Octobank 2025 trend | What to watch |
|---|---|---|---|
| Return on assets | Profit relative to total assets | Fell to 2.1% | Whether it recovers as deposits are lent out |
| Return on equity | Profit relative to shareholders’ capital | Rose to 25.1% | Whether capital keeps pace with growth |
| Deposit growth | How fast customer funding is rising | About sixfold | Stability of deposits over time |
Capital and ratings
The bank reported total capital of $84.9 million and said it received stable outlooks from both Moody’s and S&P Global. A stable outlook means the agency does not currently expect to change the rating in the near term. It is not the same as the rating itself, so anyone relying on it should check the current rating level and report directly with the agency, since ratings are updated over time.
Products for customers and businesses
Octo-Mobile app
Octobank’s retail offer is built around its Octo-Mobile app, which is where most of its customers interact with the bank. In 2025 the bank added two notable features:
- Alipay+ integration, which the bank says lets customers pay abroad at merchants that accept Alipay+ while paying from their Uzbek soum balance.
- Investment tools through the JETT platform, giving app users access to investing from within their banking app.
For travellers, paying from a soum balance abroad can be convenient, but it is still worth checking the exchange rate and any fees applied before relying on it for a whole trip. For investing features, remember that investments can fall as well as rise, unlike a deposit.
PreApprove microloans
The bank’s “PreApprove” product offers online microloans of up to UZS 100 million to eligible customers. Pre-approved lending uses data the bank already holds to offer a limit before the customer applies, which speeds up the process. As with any credit, borrowers should compare the full cost, including interest and fees, and borrow only what they can repay. Fast approval is useful in an emergency, but it also makes it easy to borrow without comparing alternatives.
Merchant acquiring
Acquiring means processing card payments for shops and other businesses. More than 15,000 companies use Octobank’s acquiring services, according to the bank, and it says it has twice received a “Best Acquiring Bank” award from Visa.
For merchants, the practical questions when choosing an acquirer are:
- Transaction fees and any monthly or terminal charges.
- How quickly funds are settled into the business account.
- Which card schemes are supported, including Uzbekistan’s domestic Uzcard and Humo systems as well as international cards.
- The quality of terminals, QR and online payment tools, and how reporting works.
- How disputes, refunds and technical faults are handled.
Digital innovation: MyID Palm in the Tashkent metro
One of the bank’s most visible projects in 2025 was the launch of biometric palm payments using MyID Palm in the Tashkent metro. MyID is Uzbekistan’s biometric identification system, and palm payment lets a registered passenger pay for travel by scanning their hand rather than tapping a card or phone. The bank presents it as fast and secure.
As with any biometric service, users should understand how their data is stored, who can access it and how to withdraw consent if they no longer want to use it. Unlike a card, a palm cannot be replaced if biometric data is ever compromised, so data protection matters more here than with ordinary payments.
The bank also launched an AI-driven video channel, OCTO-AI-TV, as part of its customer communication.
International expansion
Octobank exhibited at SIBOS 2025, the global financial services conference organised by SWIFT, held in Frankfurt, Germany. The bank says it held more than 40 meetings with banks and financial institutions from 20 countries there.
It also reported expanding its correspondent banking network to more than 55 countries, including new accounts with Santander, XJ Bank and CZBANK. Correspondent accounts are what allow a bank to send and receive international payments on behalf of customers, so a wider network matters to importers, exporters and people receiving money from abroad. The bank reported more than 100 foreign trade clients and $3.87 billion in related transaction volume in 2025.
Central Asia’s growing links with the wider world are visible beyond banking too. If you are exploring the region, our guide to why Kazakhstan should be your next travel destination covers Uzbekistan’s northern neighbour.
Awards and recognition
- Top three small banks in Uzbekistan in the CERR (Center for Economic Research and Reforms) rating.
- Stable outlooks from Moody’s and S&P Global.
- Recognition at TAF and at Brand24 Awards International, “For Dynamic Development in Uzbekistan’s Banking Sector 2024”.
- “Leader in Digital Payments” at E-commerce Central Asia Expo 2026.
- “Best Acquiring Bank” from Visa, received twice.
- Brand value reported at $30 million.
Awards are a useful signal of how a bank is seen by partners and industry bodies, but they are no substitute for audited financial statements when judging its strength.
Social projects and corporate culture
Alongside its commercial growth, the bank runs the “Mahalla Banker” project, which brings banking services and advice to local neighbourhood communities (mahallas), and financial literacy programmes for school students. It also organised its first major corporate football tournament and visited the Republican Children’s Center of Hematology and Oncology with a New Year programme for young patients.
Summing up the year, Octobank Chairman of the Management Board Iskandar Tursunov said: “2025 became a year of sustainable growth and large-scale digital transformation for Octobank. We introduced advanced solutions, expanded our international presence, and developed services focused on real customer needs. In 2026, we will continue building a digital ecosystem for businesses and individuals in Uzbekistan and beyond.”
How to assess a bank in Uzbekistan
Whether you are a local customer, a business or a foreign partner, a few checks apply to any bank in the country, Octobank included:
- Licence: confirm the bank is licensed by the Central Bank of the Republic of Uzbekistan.
- Deposit protection: check the current rules of the national deposit guarantee fund for individual deposits.
- Financial statements: read published audited reports, not just press summaries, and look at capital adequacy and asset quality.
- Ratings: check the current rating level, not only the outlook.
- Fees and rates: compare deposit rates, loan costs and card fees across several banks.
- Service and access: test the app and customer support before moving significant sums.
For companies, choosing a banking partner is part of wider finance planning; our article on how CFO advisory drives finance transformation looks at that bigger picture. If you are making a significant deposit, borrowing decision or business banking choice, speak to a qualified, independent financial adviser who knows the Uzbek market.
Frequently asked questions
What is Octobank?
Octobank is a commercial bank in Uzbekistan focused on digital banking, card acquiring and online lending. According to the bank, it serves more than 3.6 million retail customers.
How much profit did Octobank make in 2025?
The bank reported a record net profit of UZS 255.9 billion, about $21.3 million, for 2025. Total assets reached UZS 12.20 trillion over the same period.
Can Octobank customers pay abroad?
According to the bank, its Octo-Mobile app is integrated with Alipay+, allowing payments abroad at participating merchants from a soum balance. Check exchange rates and fees before you travel.
What is MyID Palm?
MyID Palm is a biometric palm payment service linked to Uzbekistan’s MyID identification system. Octobank launched it for fare payments in the Tashkent metro in 2025.
Why did Octobank’s return on assets fall?
ROA fell from 4.8% to 2.1% mainly because assets grew much faster than profit during the year. Return on equity rose to 25.1% over the same period.
Bottom line on Octobank
Octobank’s reported 2025 results show a small bank growing very fast on the back of mobile banking, acquiring and deposits. Treat the headline numbers as a starting point: check its audited statements, current ratings and fees before banking with it.
This article is general information based on the bank’s published results, not financial advice.